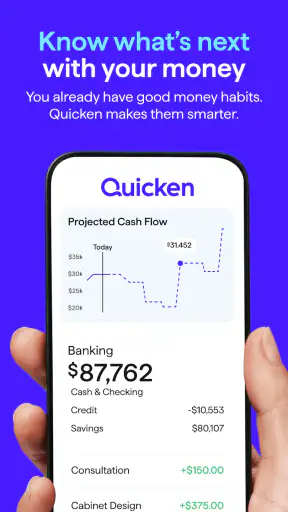
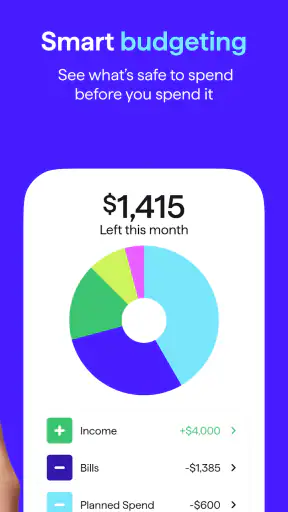
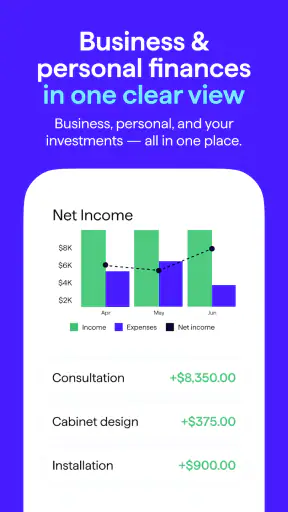
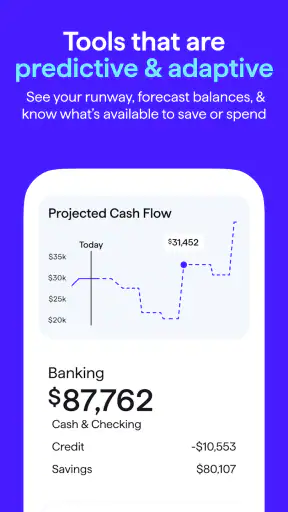
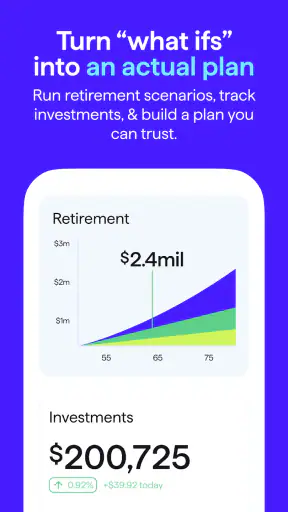
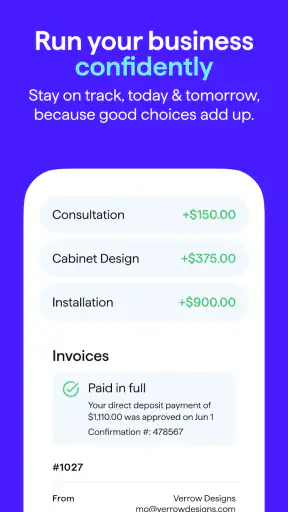
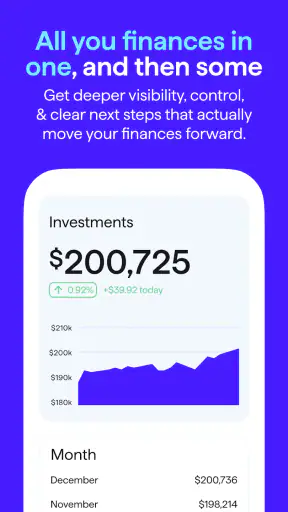
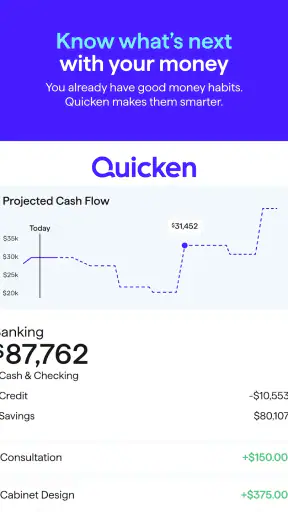
I approached Quicken: Intelligent Money as a practical money-management tool rather than a flashy budgeting experiment. Its central appeal is straightforward: it gives me one place to watch spending, organize a budget, and think about personal finances, while also making room for small-business needs. After using it in that role, my view is that it works best for people who want a broader financial picture than a simple expense tracker can provide. It is less convincing for anyone who only wants a fast way to record coffee purchases or split a dinner bill.
The app is free to install, and Quicken Inc. is the developer behind it. It belongs to the finance category, carries an Everyone age rating, and has built a 4.7 average from around 4.9 thousand ratings. That combination suggests a fairly approachable product, and my experience matches that impression: the main ideas are easy to understand, even though getting useful results depends on being willing to spend time setting up a sensible routine.
Where Quicken feels most useful in everyday money management
The strongest part of the experience is the way it encourages me to look beyond an isolated bank balance. A balance tells me what is available today; a budget asks whether that money already has a job. That distinction matters. When I use the app consistently, recurring bills, flexible spending, and business-related costs become easier to consider as separate parts of the same financial picture.
I find this especially helpful at the end of a pay period. Instead of asking whether I can afford one more purchase, I can review what has already happened and compare it with the plan I made earlier. That makes the app more useful as a decision-making aid than as a passive ledger. It does not remove the need for judgment, but it gives that judgment a clearer starting point.
A realistic example is a self-employed person who receives an irregular payment, pays household bills, buys supplies, and uses one card for both personal and work expenses. A basic notes app can record those transactions, but it quickly becomes difficult to see which spending belongs to the household and which belongs to the business. Quicken’s broader focus gives that person a reason to organize the information instead of treating every transaction as one undifferentiated stream.
That wider scope is also why I would not describe this as only a budgeting app. Budgeting is the most visible use, but the small-business angle changes how I think about it. Someone running a side project can use the same financial habit to monitor personal spending and work costs, rather than maintaining unrelated systems that never quite agree with each other.
A better workflow than checking the balance repeatedly
My preferred workflow is to review money in three passes. First, I look at recent activity and identify transactions that need attention. Second, I compare the pattern with the budget instead of reacting to a single purchase. Third, I make one or two concrete adjustments for the next period. This prevents the common mistake of opening a finance app only after something has gone wrong.
The non-obvious benefit is psychological: a budget becomes less of a restriction and more of a set of choices. If I decide in advance how much flexibility I want for eating out, transport, or hobbies, an unexpected expense is easier to evaluate. The app is valuable here not because it makes a clever prediction, but because it gives me a place to turn vague intentions into something I can revisit.
I also recommend creating a small review ritual rather than trying to maintain the app every day. A short weekly check is usually more sustainable than entering every detail immediately. People who enjoy precise daily tracking may prefer a more specialized expense tracker, but for many users, a repeatable weekly review is enough to reveal habits without making personal finance feel like a second job.
Why the small-business tools change the audience
The business support is the feature direction that most clearly separates this product from a basic household budget. It makes sense for a freelancer, contractor, or side-business owner who needs to keep an eye on work spending while still managing ordinary personal commitments. The value is not that every small business suddenly gets a full accounting department; the value is having a finance tool that acknowledges business activity instead of forcing everything into personal categories.
There is an important trade-off, though. A small business with complicated bookkeeping, payroll, inventory, multiple people approving purchases, or formal reporting requirements should not assume that a personal finance app is a replacement for professional accounting software. I would use this as an organizing and monitoring layer, not as the only system for a business whose records carry serious compliance or tax consequences.
For a sole proprietor, the best approach is to decide on categories before entering a month of transactions. Separate work supplies, travel, software, client-related costs, and personal purchases according to the way you actually make decisions. If the categories are too broad, the app becomes a collection of totals with little meaning. If they are too detailed, maintaining them becomes tiring. The useful setup is the one you can keep accurate for several months.
What I would check before relying on the numbers
Finance apps are only as helpful as the information being interpreted. I would not treat an automatically organized transaction as unquestionably correct. A purchase can look like a household expense when it was actually for work, or appear in a convenient category that does not match the way I budget. Reviewing unusual items is therefore part of the workflow, not an optional extra.
This matters most when personal and business spending overlap. I would keep receipts and supporting records separately whenever a purchase may matter later, then use the app to maintain the overview. That gives me the convenience of a central financial view without pretending that a category label alone is sufficient documentation.
The same caution applies to budgets. A budget based on an unusually cheap month can create false confidence, while one based on a particularly expensive month can feel unnecessarily punishing. I get better results by using several ordinary months as a reference and leaving room for irregular costs. Quicken can help me see the pattern, but I still have to decide which months represent normal life.
The friction that keeps it from being ideal for everyone
My main reservation is that the app asks for more commitment than its simple store presence might suggest. A person looking for a two-minute expense log may find the broader finance approach heavier than necessary. The more accounts, categories, goals, and business details I want to understand, the more important the initial organization becomes.
That is not a flaw in the idea, but it can be a real barrier. Users often download finance apps with good intentions and abandon them when the setup feels like administrative work. I would start with only the financial areas I genuinely need to monitor. Adding every possible category at the beginning makes the system look thorough, but it can make future reviews slower and less likely to happen.
The in-app purchase range is another point to consider. The app itself is free, while optional purchases are listed from $9.99 to $109.99 per item. I would therefore treat the free download as an opportunity to understand the workflow, not as a promise that every useful capability will remain free. Before paying, I would identify the specific problem I want the additional tools to solve and decide whether that benefit justifies the cost for my situation.
This is particularly important for casual users. If I only need to see a monthly spending total, paying for a broader financial system may not be worthwhile. A spreadsheet can be cheaper and more flexible for someone who enjoys building their own structure. A lightweight expense app can be faster for someone who wants almost no setup. Quicken makes more sense when the convenience of a dedicated financial environment outweighs the simplicity of those alternatives.
Where simpler alternatives may win
A spreadsheet remains a strong alternative for people who want complete control over formulas, layouts, and long-term records. It can be tailored to unusual household arrangements or a very specific freelance workflow. The downside is that I have to design and maintain the system myself, and a spreadsheet rarely provides the same guided financial routine as a purpose-built app.
A basic expense tracker is better when speed matters more than context. If my goal is simply to record cash purchases, check a daily limit, or remember who paid for something, a smaller tool may feel more comfortable. Those apps usually make fewer demands on my attention, but they also provide less help when I want to connect spending habits with a wider personal or business plan.
Traditional bank tools can be enough for users who only care about one institution. They are convenient for checking balances and recent transactions, but they may not offer the same neutral overview when money is spread across different parts of life. Quicken’s appeal is strongest when I need to think in terms of a complete financial picture rather than a single account screen.
I would also skip it if I dislike reviewing financial information altogether. No app can make an ignored budget useful. The product rewards users who are prepared to revisit categories, question unusual spending, and make small corrections. Someone who wants a completely automatic answer to “am I doing well financially?” will probably be disappointed, because financial health still requires interpretation.
Questions I would settle before installing
Is it suitable for a beginner? Yes, if the beginner starts small. I would begin with the main spending areas and one realistic budget review, then expand only after the first routine feels comfortable. The Everyone rating reflects its broad accessibility, but an approachable interface does not eliminate the need to understand basic budgeting concepts.
Can it help a household and a side business at the same time? That is one of its more attractive use cases. I would still keep the boundaries between those activities clear and maintain separate supporting records for anything important. The app can provide a useful overview, but it should not encourage careless mixing of personal and business documentation.
Is the free version enough? It may be enough for someone who wants to explore the basic money-management experience, but the presence of optional purchases means I would review the available upgrade before building my entire routine around a feature I have not confirmed is included at no cost. The sensible approach is to test the free experience first and pay only for a clearly needed improvement.
How often should it be used? I would check it weekly for ordinary budgeting and more often during a month with unusual spending. Daily use is reasonable for someone who enjoys detailed tracking, but it is not essential for everyone. Consistency matters more than frequency.
Is it a replacement for an accountant or financial adviser? No. I see it as a personal organization and monitoring tool. It can help me prepare better questions and spot patterns, but it should not be treated as professional tax, legal, or investment advice.
My recommendation for different kinds of users
I would recommend Quicken to households that want more structure than a bank app provides, freelancers who need a combined view of personal and work finances, and people who are willing to establish a recurring review habit. It is also a reasonable choice for someone who has outgrown a simple spending diary but does not want to build a financial system from scratch.
I would be more cautious with students, occasional budgeters, and users who only need a quick record of purchases. They may find a smaller tool easier to maintain. I would also steer complex businesses toward dedicated accounting software, because the needs of a growing operation can quickly exceed what a personal finance-focused workflow should handle.
The app has reached over 500 thousand installs, which gives it a meaningful user base without making popularity the main reason to choose it. I care more about whether its wider scope matches my needs. In my case, the strongest argument is the combination of household budgeting and small-business awareness; the weakest is the amount of organization required before the information becomes genuinely useful.
Final verdict on Quicken: Intelligent Money
My final impression is positive, but deliberately qualified. This is not the app I would choose for a minimal, frictionless spending log. It is the app I would consider when I want to connect budgets, personal financial decisions, and small-business activity in one more deliberate routine.
Quicken Inc. has made a finance app that rewards thoughtful use rather than rushed setup. I like that it can support a wider conversation about where money is going and what each expense means. I also appreciate that its free entry point lets people investigate the approach before considering optional purchases. At the same time, users should be honest about their tolerance for maintenance and about whether they need a full financial overview at all.
My recommendation is simple: choose it if you want a structured financial command center and are willing to review it regularly; skip it if a lightweight tracker or spreadsheet already solves your problem. For the right user, that distinction makes the app genuinely useful. For everyone else, its broader ambitions may feel like unnecessary work.


